Most ID checks still manual, warns compliance team

Most ID checks still manual, warns compliance team


Todays other news

Average mortgage shelf life falls to 13 days

Moneyfacts reveals shrinking mortgage deal availability as fluctuating swap rates...

Only 25% of £2m homes sell and 41% of flats

TwentyCi research reveals falling sales success rates for premium properties...

MAB expands dedicated lending team

Mortgage Advice Bureau appoints Ellie Edington as lending support manager...

GB Bank launches dual legal representation

GB Bank introduces a streamlined legal process for eligible property...

Instamo integrates with Fluxifi

Instamo and Fluxifi partner to streamline mortgage submissions, saving brokers...
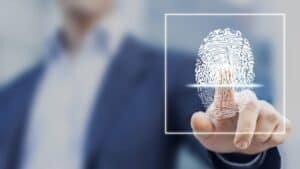
Person using fingerprint scanner for biometric security authentication.

Compliance specialist SmartSearch claims 54% of identity checks are still manual.

The FinTech supplier says the Financial Ombudsman Service’s warning about the surge in online investment and employment scams – 31,300 complaints in 2025, with 20,000 involving authorised payments – exposes a fundamental vulnerability in how businesses verify who they’re dealing with.

Advertisement

Collette Smith of SmartSearch says that, behind every one of these scams is a moment when a financial institution, an investment platform, or an employment portal failed to properly verify identity.

Advertisement

“The criminal opened an account. They passed basic checks. They looked legitimate. And then they used that legitimacy to defraud victims.

“The question isn’t whether these platforms had verification processes. It’s whether those processes could catch what criminals are deploying in 2026: AI-generated identities, deepfake documents, and synthetic profiles that pass traditional checks without triggering any alarms.”

SmartSearch recently surveyed 1,000 key decision-makers across finance, property, legal, and accounting sectors.

Some 54% of identity verification checks are still conducted manually. Only 46% are digital.

“Manual processes can’t scale to catch the volume and sophistication of modern fraud. Visual inspection doesn’t detect pixel-level document forgery,” warns Smith.

Advertisement

“Static database checks don’t identify synthetic identities built from stolen data fragments. And checks performed once at onboarding miss the evolving risk signals that emerge over time.”

Smith adds that the Financial Ombudsman Service is right to urge consumers to pause, research, and verify before transferring money, but says the burden can’t rest solely on victims. 

Smith says that this means they must do the following:

  • Automated biometric verification to catch deepfakes and synthetic identities
  • Real-time sanctions and PEP screening against global watchlists updated daily
  • Multi-source identity triangulation to detect inconsistencies across data points
  • Ongoing monitoring throughout the customer relationship, not just at onboarding
  • Enhanced due diligence for high-risk profiles, including cryptocurrency-linked accounts
Share this article ...

Join the conversation: Login and have your say

Want to comment on this story? Our focus is on providing a platform for you to share your insights and views and we welcome contributions. All comments are screened using specialist software and may be reviewed by our editorial team before publication. Introducer Today reserves the right to edit, withhold or delete comments that violate our guidelines, including those that harass, degrade, or intimidate others. Users who post such content may be banned from commenting.
By commenting, you agree to our Commenting Terms of Use.
Recommended for you
Related Articles
Domestic abusers ‘weaponise joint mortgages against women’ - claim

The cost of delay: Why affordability pressures make faster, smarter transactions a necessity

Rising affordability pressures are increasing the need for faster, more...

Controversial referral deals win qualified support after BBC report

These are interim findings of a probe following a BBC...

New TV ad campaign challenges traditional homebuying

OneDome launches a major TV campaign promoting integrated, tech-enabled homebuying...
Building Society’s fintech deal makes it a Smoove operator

Tech investment to boost broker experience

Newcastle for Intermediaries has enhanced its product transfer experience, making...

Interest rate threat and mortgage affordability cause market to stagnate

Higher mortgage costs and economic uncertainty are expected to keep...

Mortgage shock ahead as rates set to rise

Major lenders reprice deals as swap rates climb, adding further...

More mortgage rate misery to come

Rising swap rates are pushing lenders to reprice fixed deals,...
Recommended for you
Latest Features

Average mortgage shelf life falls to 13 days

Moneyfacts reveals shrinking mortgage deal availability as fluctuating swap rates...

Only 25% of £2m homes sell and 41% of flats

TwentyCi research reveals falling sales success rates for premium properties...

MAB expands dedicated lending team

Mortgage Advice Bureau appoints Ellie Edington as lending support manager...
Sponsored Content

95% LTV Second Charge Mortgages, NO ERC’s and Fixed Rates starting from 3.65%

Historically second charge mortgages or secured loans as they are...

One low rate

Lenders must say what they mean and mean what they...

Send to a friend

In order to send this article to a friend you must first login. Click on the button below to login or sign up.